Quick answer Alabama manufactured home insurance covers your home's structure, attached structures, personal belongings, liability, and extra living costs after covered losses like fire, wind, hail, and theft. Policies are written by specialty carriers or standard insurers with manufactured-home programs. Proper tie-downs, the home's age, and its location strongly affect eligibility and price. Flood damage requires separate coverage.
What is manufactured home insurance?
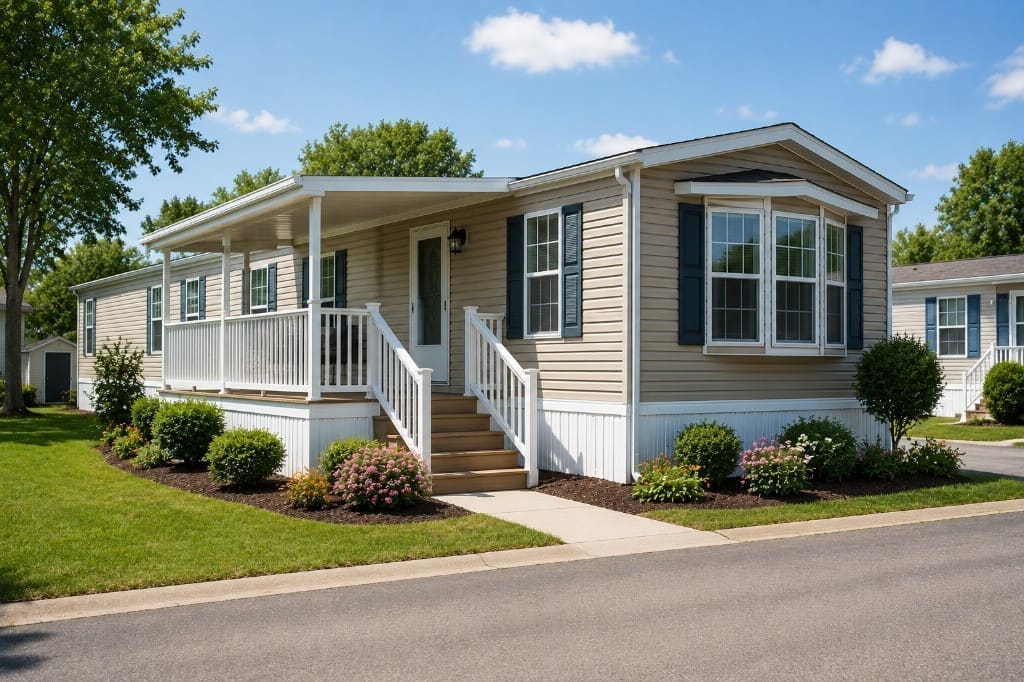
Manufactured home insurance is a homeowners-style policy designed for factory-built homes, including mobile homes and modern HUD-code manufactured homes. It covers the dwelling, other structures, personal property, loss of use, liability, and medical payments to others, just like a site-built home policy, but it's underwritten around the different construction and risks of manufactured housing.
The terms get used interchangeably, but there's a technical difference. "Mobile home" generally refers to homes built before June 15, 1976, when the federal HUD code took effect. "Manufactured home" refers to homes built after, under those federal construction standards. Insurers care about this date, because pre-1976 homes are often harder to insure.
What does manufactured home insurance cover?
Alabama manufactured home insurance generally covers the home itself, attached decks and porches, detached structures like sheds and carports, your belongings, additional living expenses, personal liability, and guest medical payments. Optional coverages may include trip collision for moving the home, replacement cost for belongings, and water backup.
| Coverage | What it protects | Alabama tip |
|---|---|---|
| Dwelling | The home's structure, including built-in appliances and fixtures | Make sure the limit reflects current replacement cost, not purchase price |
| Other structures | Sheds, carports, detached decks, skirting | Carports are easily damaged in wind; check your limit |
| Personal property | Furniture, clothing, electronics | Choose replacement cost if available |
| Loss of use | Temporary housing after a covered loss | Important after tornadoes, when repairs can take months |
| Liability | Injuries to others or damage you cause | Applies whether you own the land or rent a lot |
| Trip collision | Damage while the home is being moved | Only matters if you're relocating the home |
Why do tie-downs matter so much in Alabama?
Tie-downs and anchoring matter because unanchored or poorly anchored manufactured homes are far more likely to shift, roll, or be destroyed in high winds. Many insurers require proof of proper installation and anchoring before writing a policy, and some offer better rates for homes with documented tie-downs that meet current standards.
Alabama sees severe storms in every season: tornadoes in spring and fall, hurricanes from the Gulf in summer and early fall, and straight-line winds year-round. A manufactured home that's properly installed and anchored has a much better chance of surviving them.
Here's what to do:
- Find your installation documents. Licensed installers should leave paperwork showing how the home was set up and anchored.
- Inspect tie-downs periodically. Straps can rust and anchors can loosen over time, especially in sandy or wet soil.
- Replace what's worn. Have a qualified installer check and replace failing anchors or straps.
- Keep photos and receipts. Documentation helps with both underwriting and claims.
- Secure the skirting and add-ons. Porches, carports, and awnings can become projectiles in high winds.
Is it harder to insure an older manufactured home?
Yes. Many standard insurers limit or decline coverage for older manufactured homes, particularly those built before the 1976 HUD code. Older homes may only qualify for actual cash value coverage, which pays depreciated value, rather than replacement cost. Specialty carriers often fill this gap, though premiums and terms vary.
What helps an older home qualify:
- Updated systems: newer roofing, electrical, plumbing, and heating
- Documented tie-downs that meet current standards
- Good overall condition with no unrepaired damage
- Proper skirting and secured add-ons
- Smoke detectors and fire extinguishers
Replacement cost vs. actual cash value
This is the decision that matters most at claim time. A replacement cost policy pays what it costs to replace the home with a comparable new one. An actual cash value policy subtracts depreciation. On a 25-year-old single-wide destroyed by a tornado, an ACV settlement might be a fraction of what a new home costs. If replacement cost is available for your home, it's usually worth the extra premium.
Does it matter whether you own the land?
It can. If you own the land, your policy may need to cover detached structures, fences, and liability for the whole property. If you rent a lot in a manufactured home community, the park owner covers common areas, but you're still responsible for your home, belongings, and liability inside your lot. Some parks require tenants to carry liability coverage.
If the home sits on family land owned by a relative, make sure the policy correctly identifies who owns the home and who owns the land. Mismatches can create problems when a claim is filed.
Does manufactured home insurance cover floods?
No. Standard manufactured home policies exclude flood damage from rising water. You can buy flood coverage for a manufactured home through the National Flood Insurance Program or a private flood insurer, as long as the home is on a permanent foundation and anchored as required. Coverage typically takes 30 days to begin.
Many manufactured homes in Alabama sit in low-lying areas near rivers, creeks, and coastal marshes. If your home is in or near a flood zone, or if water has ever come close, flood coverage is worth a serious look.
How much does manufactured home insurance cost in Alabama?
Short answer Alabama manufactured home insurance costs depend on the home's age, size, value, condition, anchoring, location, and the coverage you choose. Newer, well-anchored homes inland usually cost less to insure, while older homes, coastal locations, and replacement cost coverage on high-value homes cost more. Bundling with auto can help lower the total.
Ways to save:
- Bundle your manufactured home and auto policies.
- Document tie-downs and recent upgrades.
- Install smoke detectors, deadbolts, and a monitored alarm.
- Choose a higher deductible if you can afford it.
- Keep the home well maintained to avoid small claims.
How do you get manufactured home insurance in Alabama?
To get an Alabama manufactured home insurance quote, gather the home's year, make, model, serial number, size, purchase price, installation and tie-down documents, details on upgrades, and whether you own the land or rent a lot. Then request a quote online or call a local agent who works with manufactured home carriers.
Start your quote using the form on this page or call (251) 633-5800.
Alabama manufactured home insurance FAQ
Is mobile home insurance required in Alabama?
State law doesn't require it, but lenders typically require coverage on financed homes, and many manufactured home communities require residents to carry liability insurance.
What's the difference between a mobile home and a manufactured home?
Mobile homes were built before June 15, 1976. Manufactured homes were built after that date under federal HUD construction standards. Insurers often treat pre-1976 homes differently.
Does manufactured home insurance cover tornado damage?
Yes. Wind damage from tornadoes is typically covered, subject to your deductible. Proper tie-downs can make a big difference in whether a home survives a storm.
Do I need tie-downs to get insurance?
Many insurers require proof of proper anchoring and installation, and some won't write coverage without it. Documented tie-downs can also improve your rate.
Can I insure an older mobile home in Alabama?
Often yes, though it may require a specialty carrier and may only qualify for actual cash value coverage. Updates and good condition improve your options.
Does manufactured home insurance cover flooding?
No. Flood requires a separate policy through the National Flood Insurance Program or a private flood insurer, usually with a 30-day waiting period.
What is trip collision coverage?
It covers damage to your manufactured home while it's being transported to a new location. It's usually only needed when you move the home.
How can I lower my manufactured home insurance cost?
Bundle with auto, document tie-downs and upgrades, add safety devices, choose a higher deductible, and keep the home well maintained.
Get coverage built for your home
Manufactured homes need insurance that understands how they're built and the storms they face. We'll help you find the right carrier and the right coverage for your home and your budget.
Request a free quote using the form on this page or call Branyon Insurance at (251) 633-5800.
Ready to compare Alabama manufactured home insurance?
This article is for general information only. Eligibility, anchoring requirements, valuation options, and pricing vary by carrier.